
Give employees more choices at little or no cost to your business.
With voluntary benefits, employees choose the coverage they want and usually pay for it through payroll deduction. It’s an easy way to round out a benefits package.
Already carry workers’ compensation with us? Keeping benefits with the same broker means one contact for your whole business.
Cash benefits after covered accidents.
Cash benefits for covered hospital stays.
A lump sum after a covered diagnosis.
Extra life coverage employees can buy.
Voluntary benefits are insurance plans your employees choose and pay for themselves, usually through payroll deduction. Your business sets them up and handles the deductions, but in most cases doesn’t pay the premium. Because the plan is offered through work, employees get access to coverage they might not shop for on their own.
Voluntary plans work alongside your core benefits. They’re not a replacement for a health plan, but they can help employees with costs a health plan leaves behind, such as deductibles, copays and lost income.
Cash benefits from accident, hospital and critical illness plans are usually paid to the employee, who can spend them on medical bills, rent or anything else.
Accident coverage often appeals to employees who are active on and off the job. Remember that work injuries are handled by workers’ compensation, and some accident policies cover off-the-job accidents only, while others cover both. Check the policy before you describe it to your crew.
For a small business that can’t fund a large benefits budget, voluntary plans let you offer real choices without taking on a fixed cost.
Offering every voluntary plan at once can confuse employees and split enrollment so thin that a carrier won’t issue the group. Many employers start with one or two plans that match their crew, such as accident and supplemental life, and add others later.
Ask a few employees what worries them most: a big hospital bill, missing paychecks or protecting their family. Their answers usually point to the right first plan.
Once employees enroll, the carrier bills your business each month, and you deduct each employee’s share from their paychecks. Some voluntary premiums can be deducted pre-tax under a Section 125 cafeteria plan, while others are taken after tax. The tax treatment can affect whether benefits are taxable when paid, so set this up with your payroll provider and tax professional.
Keep your deduction list matched to the carrier’s bill. When an employee leaves or changes coverage, tell the carrier and your payroll provider so deductions stop or change on time. Many voluntary policies are portable, meaning an employee may be able to keep coverage after leaving by paying the carrier directly, depending on the policy.
Many carriers require a minimum number or percentage of employees to enroll before they’ll issue a voluntary plan to a small group. Clear explanations at enrollment make a big difference, since employees can’t value coverage they don’t understand.
We help with enrollment materials and answer employee questions. Coverage is subject to the carrier’s approval and policy terms. To see how voluntary plans fit with the rest of a package, read our page on benefits for growing employers.
No call center, no runaround. You work with one licensed broker from first call to renewal.
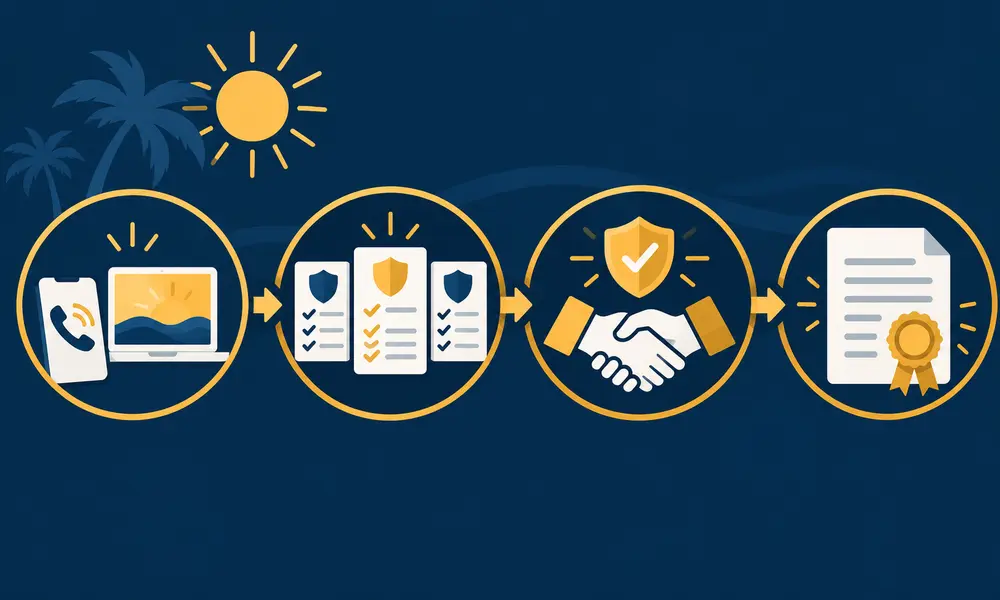
Share your industry, crew size and current coverage so we understand what you need.
We compare options from multiple carriers and explain them in plain language.
Pick your coverage, and we handle your certificates, audits and renewals.
Usually not. Employees typically pay through payroll deduction.
Many voluntary plans offer coverage without health questions up to a certain amount during the first enrollment. Larger amounts or later enrollment may require answers. It depends on the carrier and the plan.
Yes, in many cases. Some voluntary plans, such as hospital indemnity, are designed to work with a health plan, so make sure employees understand they’re not a replacement for major medical coverage.
Some can be, through a Section 125 cafeteria plan, and some are usually taken after tax. Pre-tax treatment can make benefits taxable when paid for some plans. Your tax professional can help you decide.
Usually you handle enrollment, payroll deductions and sending premiums to the carrier, and you tell the carrier about new hires and departures. Some voluntary plans may be subject to federal benefit plan rules depending on how involved the employer is. We’ll help you understand what applies.
Many voluntary policies are portable, so the employee can keep coverage by paying the carrier directly. Others end with employment. The policy or certificate will explain the rules.
Tell us about your team and what you offer today. We’ll compare options from multiple carriers.