
A practical benefits plan for growing California employers, set up and renewed with one local broker.
You don’t need an HR department to offer good benefits. We’ll help you set a budget, compare options and get your team enrolled.
Already carry workers’ compensation with us? Keeping benefits with the same broker means one contact for your whole business.
Decide what your business can contribute.
Health, dental, vision, life and voluntary plans.
We help with enrollment paperwork and questions.
We review your renewal and shop if it makes sense.
Setting up benefits for a growing team is mostly about making a few decisions in the right order. Here’s how we usually work through it with a California business owner.
A traditional group plan is the most familiar option, but it isn’t the only one. Here’s how the main choices compare at a high level:
Our small-group health page explains these options, the Small Business Health Care Tax Credit and continuation rules in more detail.
If your business had 20 or more employees in the prior year, federal COBRA generally applies to your group health plan. Smaller employers in California may be covered by their state’s continuation law instead, which usually allows a shorter continuation period. The carrier or a COBRA administrator often handles notices, but you need to report terminations promptly. This is general information, not legal advice.
Before each renewal, we review the carrier’s new rates and plan changes, look at how employees used the plan, and compare other options if it makes sense. If you stay, we help with open enrollment. If you switch, we help with the transition and timing so there isn’t a gap.
Because we also handle workers’ compensation and business insurance, your employee count, payroll and benefits changes go through one contact. See the full range of plans on our employee benefits page.
No call center, no runaround. You work with one licensed broker from first call to renewal.
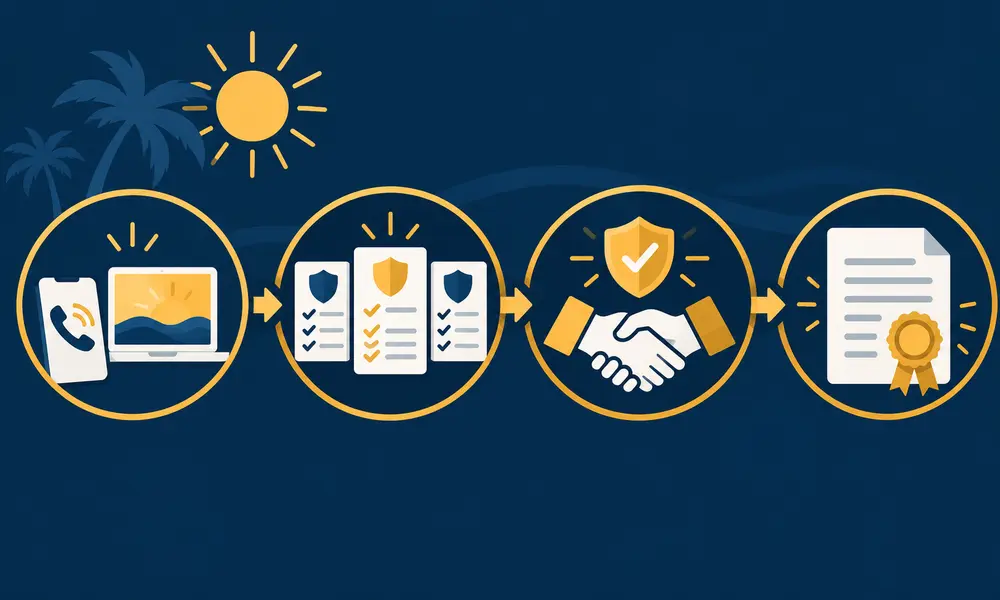
Share your industry, crew size and current coverage so we understand what you need.
We compare options from multiple carriers and explain them in plain language.
Pick your coverage, and we handle your certificates, audits and renewals.
Often, yes. Even a simple dental and vision plan can help you hire and keep good people. We’ll show you options at different budgets.
Usually a list of eligible employees with dates of birth, ZIP codes and the coverage they’re likely to choose, plus your business address and current plan details if you have one. We’ll send a simple census form to fill out.
Usually yes, if they’re on payroll and meet the plan’s eligibility rules. Some programs and carriers have rules about groups made up only of owners and family members, so we’ll check before quoting.
You choose, within limits. Federal rules cap waiting periods for group health at 90 days, and many employers use the first of the month after 30 or 60 days. Carriers may offer set options.
Many employers can move a group plan to a new carrier at different points in the year, but switching mid-year can reset deductibles for employees. We usually recommend reviewing changes ahead of your renewal date.
Benefits usually must be offered on the same terms to employees in the same eligibility class, such as full-time employees. Tax rules also limit plans that favor owners or highly paid employees. We’ll explain the rules for each plan.
Tell us about your team and what you offer today. We’ll compare options from multiple carriers.