
Income protection for your employees and their families if they can’t work or pass away.
Group life and disability coverage helps employees and their families if the unexpected happens. Workers’ compensation covers work injuries; disability coverage can help with illnesses and injuries that happen off the job.
Already carry workers’ compensation with us? Keeping benefits with the same broker means one contact for your whole business.
A benefit paid to an employee’s family if they pass away.
Partial income while an employee recovers from an illness or injury.
Income protection for longer-lasting disabilities.
You choose who pays.
Group term life insurance pays a benefit to an employee’s beneficiary if the employee dies while covered. Employers usually offer a flat amount for everyone or a multiple of each employee’s salary. Many plans also include accidental death and dismemberment (AD&D), which pays an added benefit for covered accidental deaths and certain serious injuries.
Group term life usually ends or must be converted when an employee leaves. Many policies let a departing employee convert to an individual policy or keep coverage under a portability feature, within a deadline. Make sure departing employees know about it.
Under IRS rules, the cost of employer-provided group term life coverage up to $50,000 is not taxable to the employee. If you provide more than $50,000, the cost of the coverage above $50,000, figured using the IRS premium table, is included in the employee’s income and is subject to Social Security and Medicare taxes.
This is called imputed income, and it shows up on the employee’s W-2 even though they never received cash. Your payroll provider usually handles the calculation, but they need to know the coverage amounts. Talk with your tax professional if you’re considering higher benefits for owners or key employees.
Disability insurance replaces part of an employee’s income when an illness or injury keeps them from working. Benefits are usually a percentage of pay, up to a monthly or weekly maximum.
Many group disability policies limit coverage for pre-existing conditions during the first period an employee is covered. Read the policy definitions closely, especially how it defines being unable to work at your own occupation or any occupation.
Workers’ compensation pays medical bills and lost wages for injuries and illnesses that arise from the job. It’s required for most California employers. Disability insurance is a benefit you choose to offer, and it usually covers the much more common situation: illness or injury that has nothing to do with work, such as a car accident on a weekend or a heart condition.
Group disability policies usually exclude or reduce benefits for work injuries that workers’ compensation covers. That’s why the two work together rather than overlap. For your crew’s job-site risk, see our page on workers’ compensation in California.
Life and disability can be employer-paid, shared or fully employee-paid. Who pays the disability premium can affect whether benefits are taxable to the employee. In general, benefits paid from an employer-paid plan may be taxable income, while benefits from a plan the employee paid with after-tax dollars may not be. Your tax professional can explain how this applies to your plan design.
Employee-paid supplemental life and disability are often offered as voluntary benefits through payroll deduction.
We compare plan designs from multiple carriers, explain eligibility and elimination periods, and help you enroll employees. Each renewal, we review your rates and coverage. For coverage on an owner or key person, our life insurance page covers individual and business options.
No call center, no runaround. You work with one licensed broker from first call to renewal.
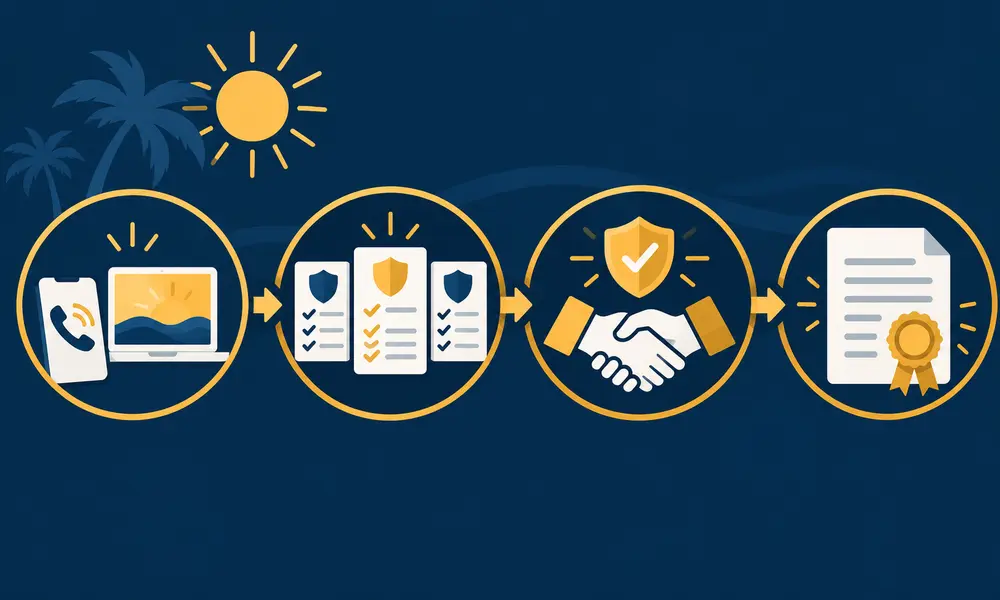
Share your industry, crew size and current coverage so we understand what you need.
We compare options from multiple carriers and explain them in plain language.
Pick your coverage, and we handle your certificates, audits and renewals.
Workers’ compensation covers work-related injuries and illnesses. Group disability can help with conditions that happen off the job.
Usually not for the basic amount. Many group plans offer a guaranteed issue amount without health questions. Higher amounts or late enrollment may require a health questionnaire, depending on the carrier.
It’s the waiting time between when a disability starts and when benefits begin. Short-term disability plans usually have a short elimination period, and long-term plans a longer one. A longer elimination period usually lowers the premium.
The cost of employer-provided coverage over $50,000 is treated as taxable income to the employee under IRS rules, using the IRS premium table. Your payroll provider usually reports it on the W-2. Your tax professional can confirm how it applies to you.
Many policies offer conversion to an individual policy or portability to keep group coverage, if the employee applies within a set deadline. Terms vary by carrier, so check the certificate of coverage.
Many short-term disability policies treat recovery from childbirth like other medical conditions, depending on the policy. Pre-existing condition limits may apply if coverage started recently. We’ll show you how each plan handles it.
Tell us about your team and what you offer today. We’ll compare options from multiple carriers.