
Affordable benefits your crew will actually use, offered on their own or alongside health coverage.
Dental and vision plans are among the most-used benefits and cost far less than medical coverage. You can pay for them, share the cost, or offer them as voluntary benefits.
Already carry workers’ compensation with us? Keeping benefits with the same broker means one contact for your whole business.
Preventive care, fillings and major services, depending on the plan.
Eye exams, glasses and contacts.
Employer-paid, shared or employee-paid options.
Offer them with or without a medical plan.
Most group dental plans sort care into three tiers. Preventive care, such as cleanings, exams and routine X-rays, is often covered at the highest level. Basic services, such as fillings and simple extractions, are usually covered at a lower percentage. Major services, such as crowns, bridges and dentures, are usually covered at the lowest level. Many plans also have an annual deductible and an annual maximum, which is the most the plan pays per person each year.
Orthodontic coverage, when it’s included, often applies only to children and may have its own lifetime maximum. Check the plan summary before you promise it to employees.
The two most common plan types work very differently.
DHMO networks vary a lot by area. Before choosing one, check whether there are participating dentists near where your employees live and work.
Many dental plans use waiting periods: a set time before basic or major services are covered. Preventive care usually starts right away. Waiting periods are more common on voluntary plans and smaller groups, and some carriers waive them when you switch from another group dental plan with proof of prior coverage.
Some plans also apply stricter rules to late enrollees, meaning employees who skip their first chance to enroll and join later. Telling employees about this at enrollment avoids surprises.
Vision plans usually cover a routine eye exam, plus an allowance for either glasses (frames and lenses) or contact lenses, on a set schedule such as once every 12 or 24 months depending on the plan. Employees usually get the most value at in-network providers. Many plans include discounts on lens upgrades and, in some cases, laser vision correction.
Routine vision plans are not medical coverage for eye disease or injury. Those are usually handled by your small-group health plan.
You have three main ways to fund dental and vision:
Employee premium shares for group dental and vision can often be paid pre-tax through a Section 125 cafeteria plan. Ask your payroll provider or tax professional how to set that up. For other employee-paid coverage, see our page on voluntary benefits.
We compare plan designs from multiple carriers, check networks against where your employees live, and help with enrollment forms. At renewal we review rate changes and whether the plan is still a good fit. If you’re building a full package, our employee benefits overview shows how dental and vision fit with health, life and disability.
No call center, no runaround. You work with one licensed broker from first call to renewal.
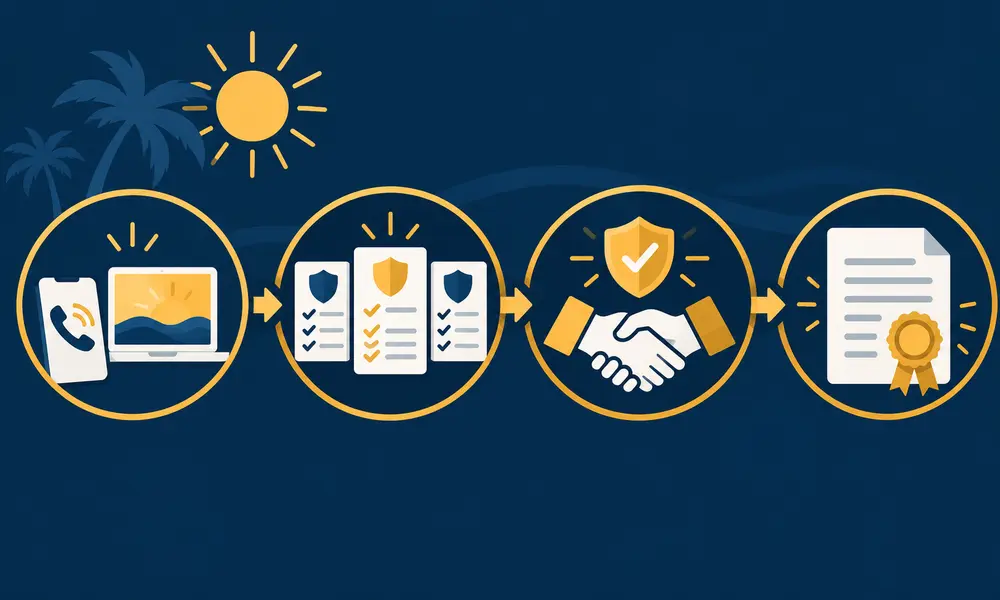
Share your industry, crew size and current coverage so we understand what you need.
We compare options from multiple carriers and explain them in plain language.
Pick your coverage, and we handle your certificates, audits and renewals.
Yes. Many businesses start with dental and vision on their own.
It’s the most a dental plan will pay for one person’s care in a plan year. Once it’s reached, the employee pays the rest until the plan year resets. DHMO plans often don’t have one, while most PPOs do.
Many plans have waiting periods for basic and major services, while preventive care usually starts right away. Some carriers waive waiting periods when your group moves from another dental plan. We’ll show you each plan’s rules.
With a dental PPO, employees can see any dentist, though they usually pay less in network. With a DHMO, they need to pick a dentist from the plan’s network. We can check whether specific dentists participate.
Participation rules vary by carrier and are often different for employer-paid and voluntary plans. Small groups may need a minimum number of enrollees. We’ll confirm the requirements before you choose.
Usually not. Routine vision plans focus on eye exams, glasses and contacts. Medical eye care is usually covered by a health plan, depending on that plan’s terms.
Tell us about your team and what you offer today. We’ll compare options from multiple carriers.