
Health plans for growing employers, compared across multiple carriers, with help at setup and renewal.
A group health plan helps you hire and keep good people. Carriers set their own rules for employer contributions and employee participation, so we compare plans and explain the trade-offs before you choose.
Already carry workers’ compensation with us? Keeping benefits with the same broker means one contact for your whole business.
PPO, HMO and high-deductible plan options from multiple carriers.
Choose how much of the premium your business pays.
High-deductible plans that pair with a health savings account.
We review your renewal and compare options each year.
Small-group health insurance is a medical plan your business buys for its employees, usually with the option to add spouses and children. In California, the small-group market covers employers with 1 to 100 employees, a wider range than the federal default of 50.
Small-group plans follow Affordable Care Act rules that matter to employers. Carriers can’t set your premium based on your employees’ health history. Premiums can vary only by a short list of factors, such as age, family size and location, and each of those has limits.
Two rules shape almost every small-group plan. The first is the employer contribution: the share of the premium your business pays. Most carriers require you to pay at least a minimum percentage of employee-only coverage. The exact percentage varies by carrier.
The second is participation: the share of eligible employees who must enroll. Each carrier sets its own minimum, and many don’t count employees who decline because they already have coverage elsewhere, such as through a spouse.
One exception is worth knowing. Under federal rules, employers that miss the participation requirement can generally still buy small-group coverage during an annual window from November 15 to December 15. We’ll tell you if that window fits your situation.
A small-group plan can usually start any month of the year. After that, your plan has its own annual open enrollment period before each renewal, when employees can join, drop or change plans.
You can set a waiting period before new hires become eligible, but federal rules cap it at 90 days. Outside open enrollment, employees and their families can usually enroll mid-year after a qualifying event, such as marriage, a new baby or losing other coverage. These are special enrollment periods, and they come with deadlines, so tell us about changes when they happen.
Some employers can claim a federal tax credit for part of what they pay toward employee premiums. According to the IRS, you generally must:
The credit can be claimed for only two consecutive tax years, and it’s largest for the smallest, lowest-wage employers. SHOP plan choices vary by state, so the credit doesn’t make sense for every business. Your tax professional should confirm eligibility.
If a group plan doesn’t fit, a health reimbursement arrangement (HRA) may. With an HRA, your business reimburses employees tax-free for individual health insurance premiums and, depending on the design, some medical costs.
Employees in either arrangement need their own qualifying health coverage.
A premium-only plan is the simplest form of a Section 125 cafeteria plan. It lets employees pay their share of group health premiums with pre-tax payroll deductions, which can lower taxable wages for the employee and payroll taxes for the business. It needs a written plan document. Ask your tax professional how it applies to owners, since some owners, such as more-than-2% S corporation shareholders, are treated differently.
Federal COBRA generally applies to employers with 20 or more employees. It lets departing employees and their families keep the group plan, usually for 18 months and in some cases up to 36 months, at up to 102% of the full premium.
Smaller California employers with 2 to 19 employees fall under Cal-COBRA instead, which generally allows up to 36 months of continuation for insured group plans. Cal-COBRA can also extend coverage for people whose federal COBRA runs out before 36 months. We’ll help you understand which rules apply to your plan. This is general information, not legal advice.
We quote plans from multiple carriers, help your team enroll and review each renewal. Because we also handle workers’ compensation, we see your whole employee picture. If you want to look at health alongside other benefits, start with our employee benefits page.
No call center, no runaround. You work with one licensed broker from first call to renewal.
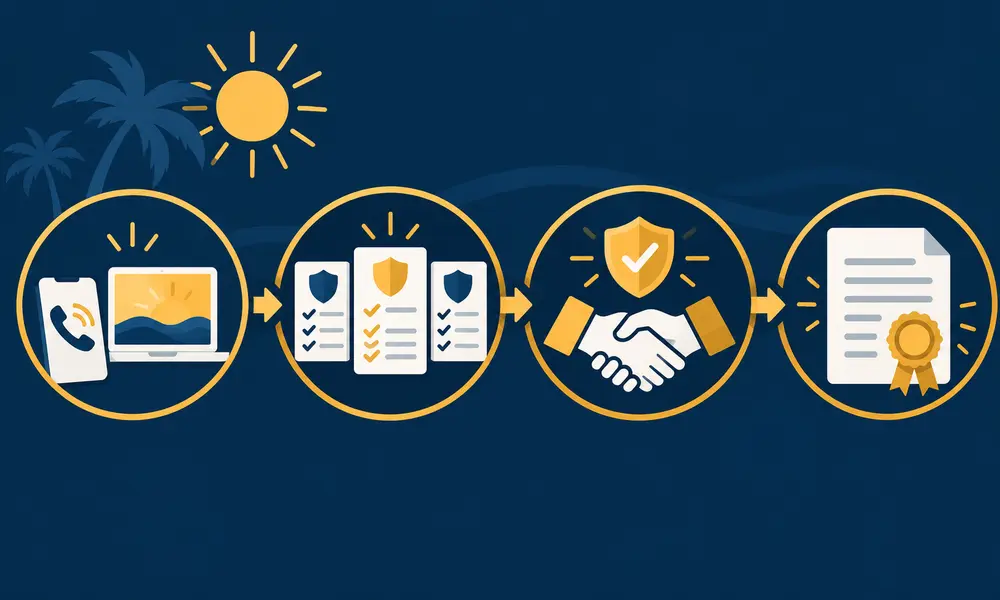
Share your industry, crew size and current coverage so we understand what you need.
We compare options from multiple carriers and explain them in plain language.
Pick your coverage, and we handle your certificates, audits and renewals.
Many carriers offer small-group plans for businesses with as few as two employees, including the owner in some cases. Rules vary by carrier.
Most carriers require the employer to contribute a minimum share of employee premiums. We’ll explain each carrier’s rules.
Usually contributions must be applied consistently to similar groups of employees, and the Small Business Health Care Tax Credit requires a uniform percentage. Many plans allow different contribution levels for employee and dependent coverage. We’ll explain what each carrier allows.
For the small business health program, you need at least one employee who isn’t an owner, a spouse of an owner or a family member of an owner. Private carriers have their own rules about owner-only groups. We’ll check this before quoting.
Many carriers don’t count employees with other coverage against your participation requirement. They usually need to sign a waiver showing they declined. Rules vary, so we’ll confirm with each carrier.
Employers in California with fewer than 50 full-time equivalent employees generally aren’t subject to the federal employer mandate. Offering health coverage is usually a business decision, made to help you hire and keep people.
Tell us about your team and what you offer today. We’ll compare options from multiple carriers.