
Dream Safe Insurance helps employers with growing employers find the right mix of medical, dental, vision and ancillary coverage—without overpaying.
Offer the benefits your team values, at a budget that works for your business.
Health plans for growing California employers, quoted across multiple carriers so you can compare costs side by side.
Affordable benefits your crew will actually use, offered on their own or alongside health coverage.
Income protection for your employees and their families if they can’t work or pass away.
A practical benefits plan for growing and mid-size California employers. We shop multiple carriers, explain what each plan covers and help you pick the package that fits your team and your budget.
Few local agencies handle both business insurance and group benefits. With one broker, your renewals, payroll questions and employee changes go to one place.
No call center, no runaround. You work with one licensed broker from first call to renewal.
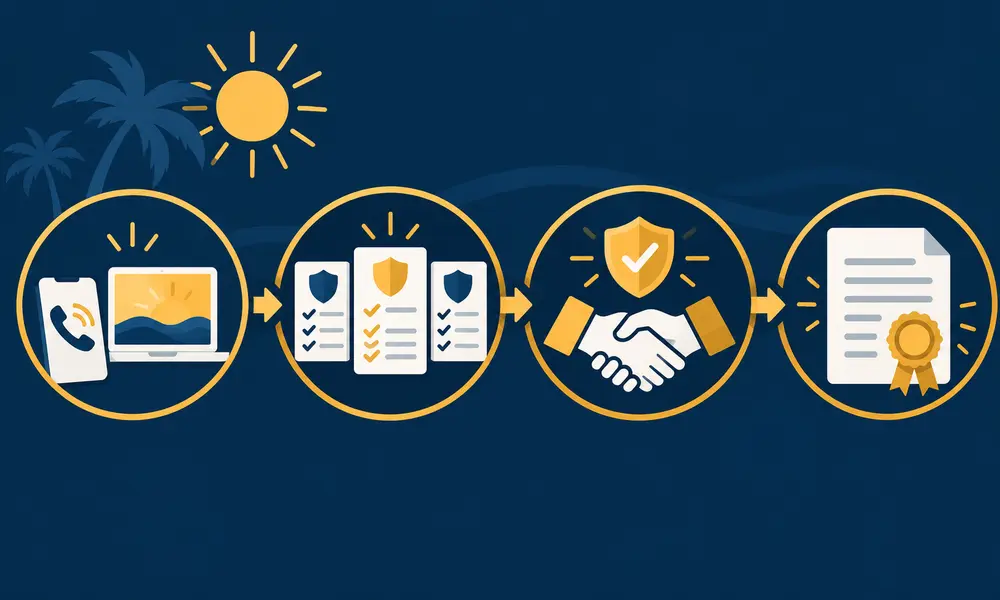
Share your industry, crew size and current coverage so we understand what you need.
We compare options from multiple carriers and explain them in plain language.
Pick your coverage, and we handle your certificates, audits and renewals.
We’re not tied to one insurance company. We shop several carriers to find the right fit for your business, your team or your family.
Employee benefits are the coverage you offer on top of pay: health, dental, vision, life, disability and voluntary plans. For a growing business, the hard part usually isn’t wanting to offer benefits. It’s knowing what’s allowed, what it will cost you and how much paperwork comes with it.
Most employers build their package in layers. Some start with group health. Others start with dental and vision, add life and disability later, and use voluntary plans to fill gaps. There’s no single right order. What matters is that the plan fits your budget, your crew and how you hire.
Under the Affordable Care Act, the small-group and large-group health markets operate under different rules for plan design and pricing. In California, carriers set their own guidelines about minimum group size, so whether you have a small team or a large workforce, there are options worth comparing.
A good first step is to decide what you can spend each month and what problem you’re trying to solve. A roofing company losing workers to bigger competitors needs a different plan than an office with five long-time staff.
If you’re comparing several of these at once, our page on employee benefits walks through how employers usually put a package together.
Most employers in California can offer a benefits package even if they have never done it before. The process starts with a census—a simple list of each employee’s age, zip code and coverage tier (employee-only, employee-plus-spouse, family, etc.). Your broker sends that census to several carriers, and within a few business days you receive quotes you can compare side by side.
An independent broker doesn’t work for one carrier. We gather your employee census, compare plans from multiple carriers, explain contribution and participation rules, and help your team enroll. At renewal we review the carrier’s new rates and plan changes, and shop the market if it makes sense.
In most cases, brokers are paid by the carrier through commissions built into the premium, so you usually don’t pay a separate fee for this help. Ask us how we’re paid on any plan we recommend, and we’ll tell you.
Yes. Many employers start with dental, vision, life or voluntary plans and add health coverage later. Some also look at a health reimbursement arrangement, where the business reimburses employees for individual health insurance under IRS rules.
It depends on the plan and the carrier. Most group plans set an hours requirement for eligibility, and many use 30 hours a week as full-time. We’ll explain each plan’s eligibility rules before you choose.
Employers can usually start a group health plan any month of the year, not only during the individual open enrollment season. Dental, vision, life and voluntary plans can usually start any month as well, depending on the carrier.
There is a federal Small Business Health Care Tax Credit for some employers with fewer than 25 full-time equivalent employees who buy coverage through the small business health program and pay at least half of employee-only premiums. It can only be claimed for two consecutive years, so talk with your tax professional about whether it applies.
Tell us about your team and what you offer today. We’ll compare options from multiple carriers.